

When the bond market starts pricing the GPU, the equity tape follows.
The neo cloud trade was built on one assumption - that capital would always be there. Credit markets are now questioning that premise. CoreWeave's unsecured bonds due 2032 traded below 80 cents on the dollar, the line widely treated as distress, with yields of around 15% on its 2031 and 2032 notes. The stock fell roughly 15.5% on Wednesday and slipped again after hours. Nebius, IREN and Applied Digital fell about 9-12% with it. This was not an earnings miss. It was a financing scare. In a business where the product is borrowed money turned into rented GPUs, a financing scare is the one that matters.
Duration Mismatch?
Neo clouds are long-duration borrowers running short-duration contracts on assets that depreciate faster. That mismatch is fine when rates fall and credit is open. Hotter inflation data has put a second Fed rate hike back on the table this month, and the cost of insuring AI-infrastructure debt has hit record highs. The question has moved from "how fast can they grow" to "can they service the debt through a pricing reset". When credit leads, equity usually follows.
A Discerning Equity Tape
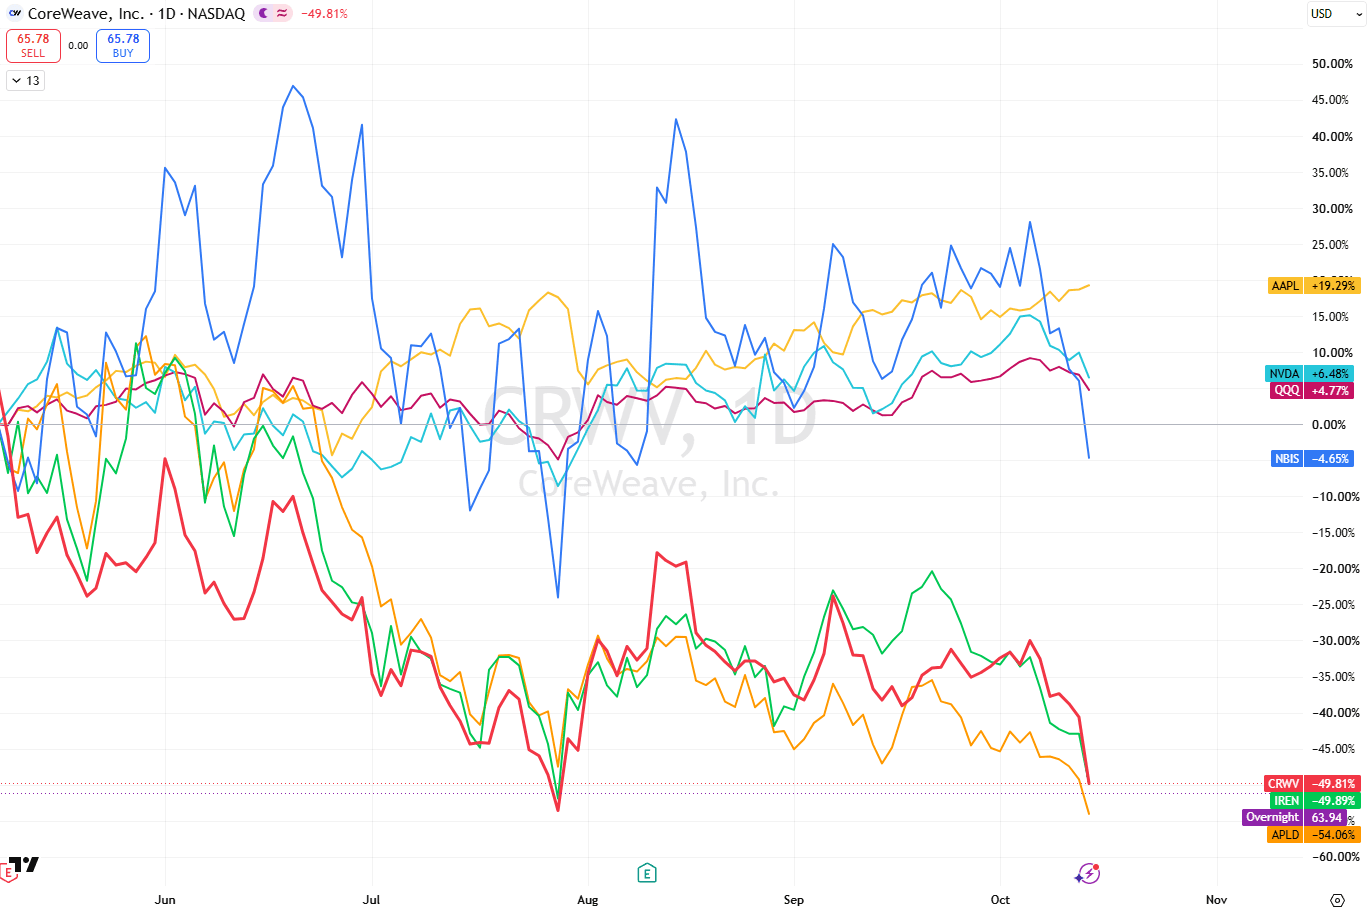
The drawdowns are no longer corrections. As of Oct 14, CoreWeave has fallen about 50% over the last six months. IREN and Applied Digital are each down 50-55% over the same period. Nebius has held up better, but is still down over 30% since June. Nvidia, by contrast, is up 6.5% and the broader QQQ up nearly 5%. Apple is up nearly 20%. This is a discerning tape, not an indiscriminate one. The market is not selling AI. It is selling leverage to AI.
A Worsening, But Differentiated Credit Tape
Name | Price / drawdown from 52-wk high | Debt & funding | Key facility / credit signal |
CoreWeave (CRWV) | $65.78 / -65% vs $187 high (Jun, 2025) | ~$52B debt + leases (end-June); ~5.8x annualised Q2 EBITDA; Q2 interest $640M | 2032 9.625% notes <80c, YTM ~14.8–15%; unsecured spread ~1,000bp; CDS at record |
Nebius (NBIS) | $186.01 / -38% vs 297 high (Jun, 2026) | $8.5B debt vs $8.0B cash (end-June); $5.75B converts (Aug) | $775M GPU/contract-backed loan, SOFR+250, matures Oct 31 2030 |
IREN (IREN) | $30.56 / -60% vs 76.87 high (Nov, 2025) | $6.7B converts | $9.7B Microsoft + $3.4B Nvidia contracts; GPU financing 6% (IG) / 9% (non-IG) |
Applied Digital (APLD) | $20.33 / -60% vs 50.73 high (May, 2026) | ~$6.4B debt | Landlord model; leases to hyperscale tenants |
NVDA / QQQ (ref.) | $221.3/ -9% vs 243.37 high (Oct, 2026) | $728.95 / -4.5% vs 762.86 high (Oct, 2026) | — | NVDA CDS also at highs |
CoreWeave is the bellwether. Its 9.625% 2032 notes yield about 15% and its 9.75% 2031s about 14.9% . The 2032 yield rose about 1.5 percentage points in a week. Spread crossed roughly 1,000bp. CDS on CoreWeave and Oracle hit record highs, at 982bp and 288bp respectively. Oracle’s 6.25% 2032 bonds yield 7.3-7.4%, a sign that the stress is spreading to investment-grade AI borrowers as well. Even NVDA has seen CDS spreads widen, from c40bp in Jun to 91bp now. Higher financing/ re-financing costs also raise the bar for realizing economic profits. CoreWeave's co-founder is now courting insurers' "effectively unlimited" capital. The market read - “"need more money, don’t have enough”.
The Balance Sheet Problem
CoreWeave raised more than $35 billion this year through chip-backed loans, high-yield bonds, convertibles and equity. That took debt and lease obligations to about $52 billion at end of 2Q. Second-quarter interest expense more than doubled year on year to $640 million, and debt stood at about 5.8x annualised Q2 EBITDA. Management guides Q3 interest to $860-940 million and 2026 capex to $35-39 billion. Visible Alpha consensus sees roughly $25 billion of negative free cash flow this year. CreditSights' Jordan Chalfin put the bear case in one line, if there is an overbuild, why would customers renew with CoreWeave?
Nebius is better funded - $8.0 billion of cash against $8.5 billion of debt at end-June. It leans on convertibles, including $5.75 billion closed in August, with customer prepayments expected to exceed $9 billion in 2026. It also has a first secured $775 million facility backed by GPUs and an investment-grade contract at SOFR plus 250. IREN is anchored by a $9.7 billion Microsoft contract. Applied Digital carries about $6.4 billion of debt as a landlord to the buildout.
The structural vulnerability in AI infra models lies in depreciation. Since adjusted EBITDA strips out GPU depreciation, changes to useful-life assumptions distort reported profitability. For example, Nebius boosted its metrics in 2026 by extending server lifespans from four to five years. While some analysts point to an easing of spot pricing from historical highs, contract rental rates for NVIDIA H100s actually remain up significantly year-to-date due to structural capacity constraints. However, if macro supply shocks finally normalize and rental yields catch up to a standard secondary-market depreciation curve, the underlying collateral backing GPU-backed debt could quickly become worth less than underwriting models assume.
The Rebuttal from Bulls
The bulls' arguments are also real. Backlog is contracted, often with investment-grade counterparties - Microsoft and Meta at Nebius, and Microsoft and Nvidia at IREN. Secured facilities price at investment-grade-like spreads, from SOFR plus 225 to 300, because lenders underwrite the contract, not the chip. Prepayments now cover 45-60% of GPU capex at IREN and Nebius, and operators report payback periods of about two years. Nvidia is a shareholder and a backstop customer. A 15% yield on a contracted-cashflow business could be an opportunity, but the question is whether cash flows will be enough to service the debt.
The counter-argument is that contracts are only as good as their renewal. Holding companies' unsecured debt sits behind the secured silos, and that is exactly the tranche now trading in the 70s.
The Contagion Risk
Nvidia is both vendor and financier to this ecosystem, and even its CDS has more than doubled to 91bp over the last three months. As covered in our recent outlook report, hedging long AI equity positions through AI credit default swaps is an opportunity. Nvidia, for example, is not the epicentre but a next-order exposure. Oracle is the investment-grade proxy - its stock fell nearly 9% Wednesday and its bonds slipped. Private credit and insurers are the marginal lenders. If the CoreWeave insurer pitch stalls, the funding chain tightens. Data-center REITs and power developers have the long leases on the other side of the mismatch, so a renewal problem at a neocloud becomes a vacancy problem for a landlord. Broad cloud software has held up so far, and SKYY has been resilient, which says the market sees this as a leverage problem, not a demand problem.
What to Watch
Date | Event | Why it matters |
Late Oct 2026 | FOMC - market pricing a second hike after hotter inflation data | Floating-rate DDTLs & refinancing cost |
Nov 4, 2026 | Applied Digital AGM | Lease-up and funding update |
Nov 10, 2026 | Nebius Q3 | Capex, prepayments, next secured deal |
Nov 10, 2026 | CoreWeave Q3 results | Interest guide $860-940M; capex $35-39B; FCF |
Nov 17, 2026 | IREN fiscal Q1 (expected date) | Microsoft ramp, GPU financing |
Ongoing | CRWV 2031/2032 bond prices, CDS, insurer financing (FT) | 80c line = distress threshold |
The FOMC later this month and the rate path. Applied Digital AGM on Nov 4. Nebius on 10 Nov. CoreWeave's Q3 on Nov 10, which is the big one - interest expense against guidance, capex discipline, renewal commentary and any new secured or insurer-backed deal. Daily, watch the CoreWeave 2032 bond around the 80-cent line, CDS prints, and whether Nvidia decouples or follows.
Strategy & Positioning
Respect the credit signal. When bonds trade at distressed levels, equity rallies tend to be sold until the financing question is answered. Separate the capital structures. Secured, contract-backed paper and better-capitalised names like Nebius, with near net-neutral cash against debt, deserve a different multiple from holding-company unsecured risk. Pairs make more sense than outright shorts - the market is distinguishing leverage from AI demand - long quality AI compute versus short the most levered neo clouds expresses the view with less beta. Options are expensive after this volume, so defined-risk structures beat naked exposure.
Triggers to turn constructive - CoreWeave bonds back above 85-90 cents, a large financing done at sane terms, or a rate-path pivot. Triggers to get more defensive - a missed interest guide, a renewal or customer wobble, or Nvidia breaking down with its customers.
The cloud isn't the problem. The leverage underneath it is.